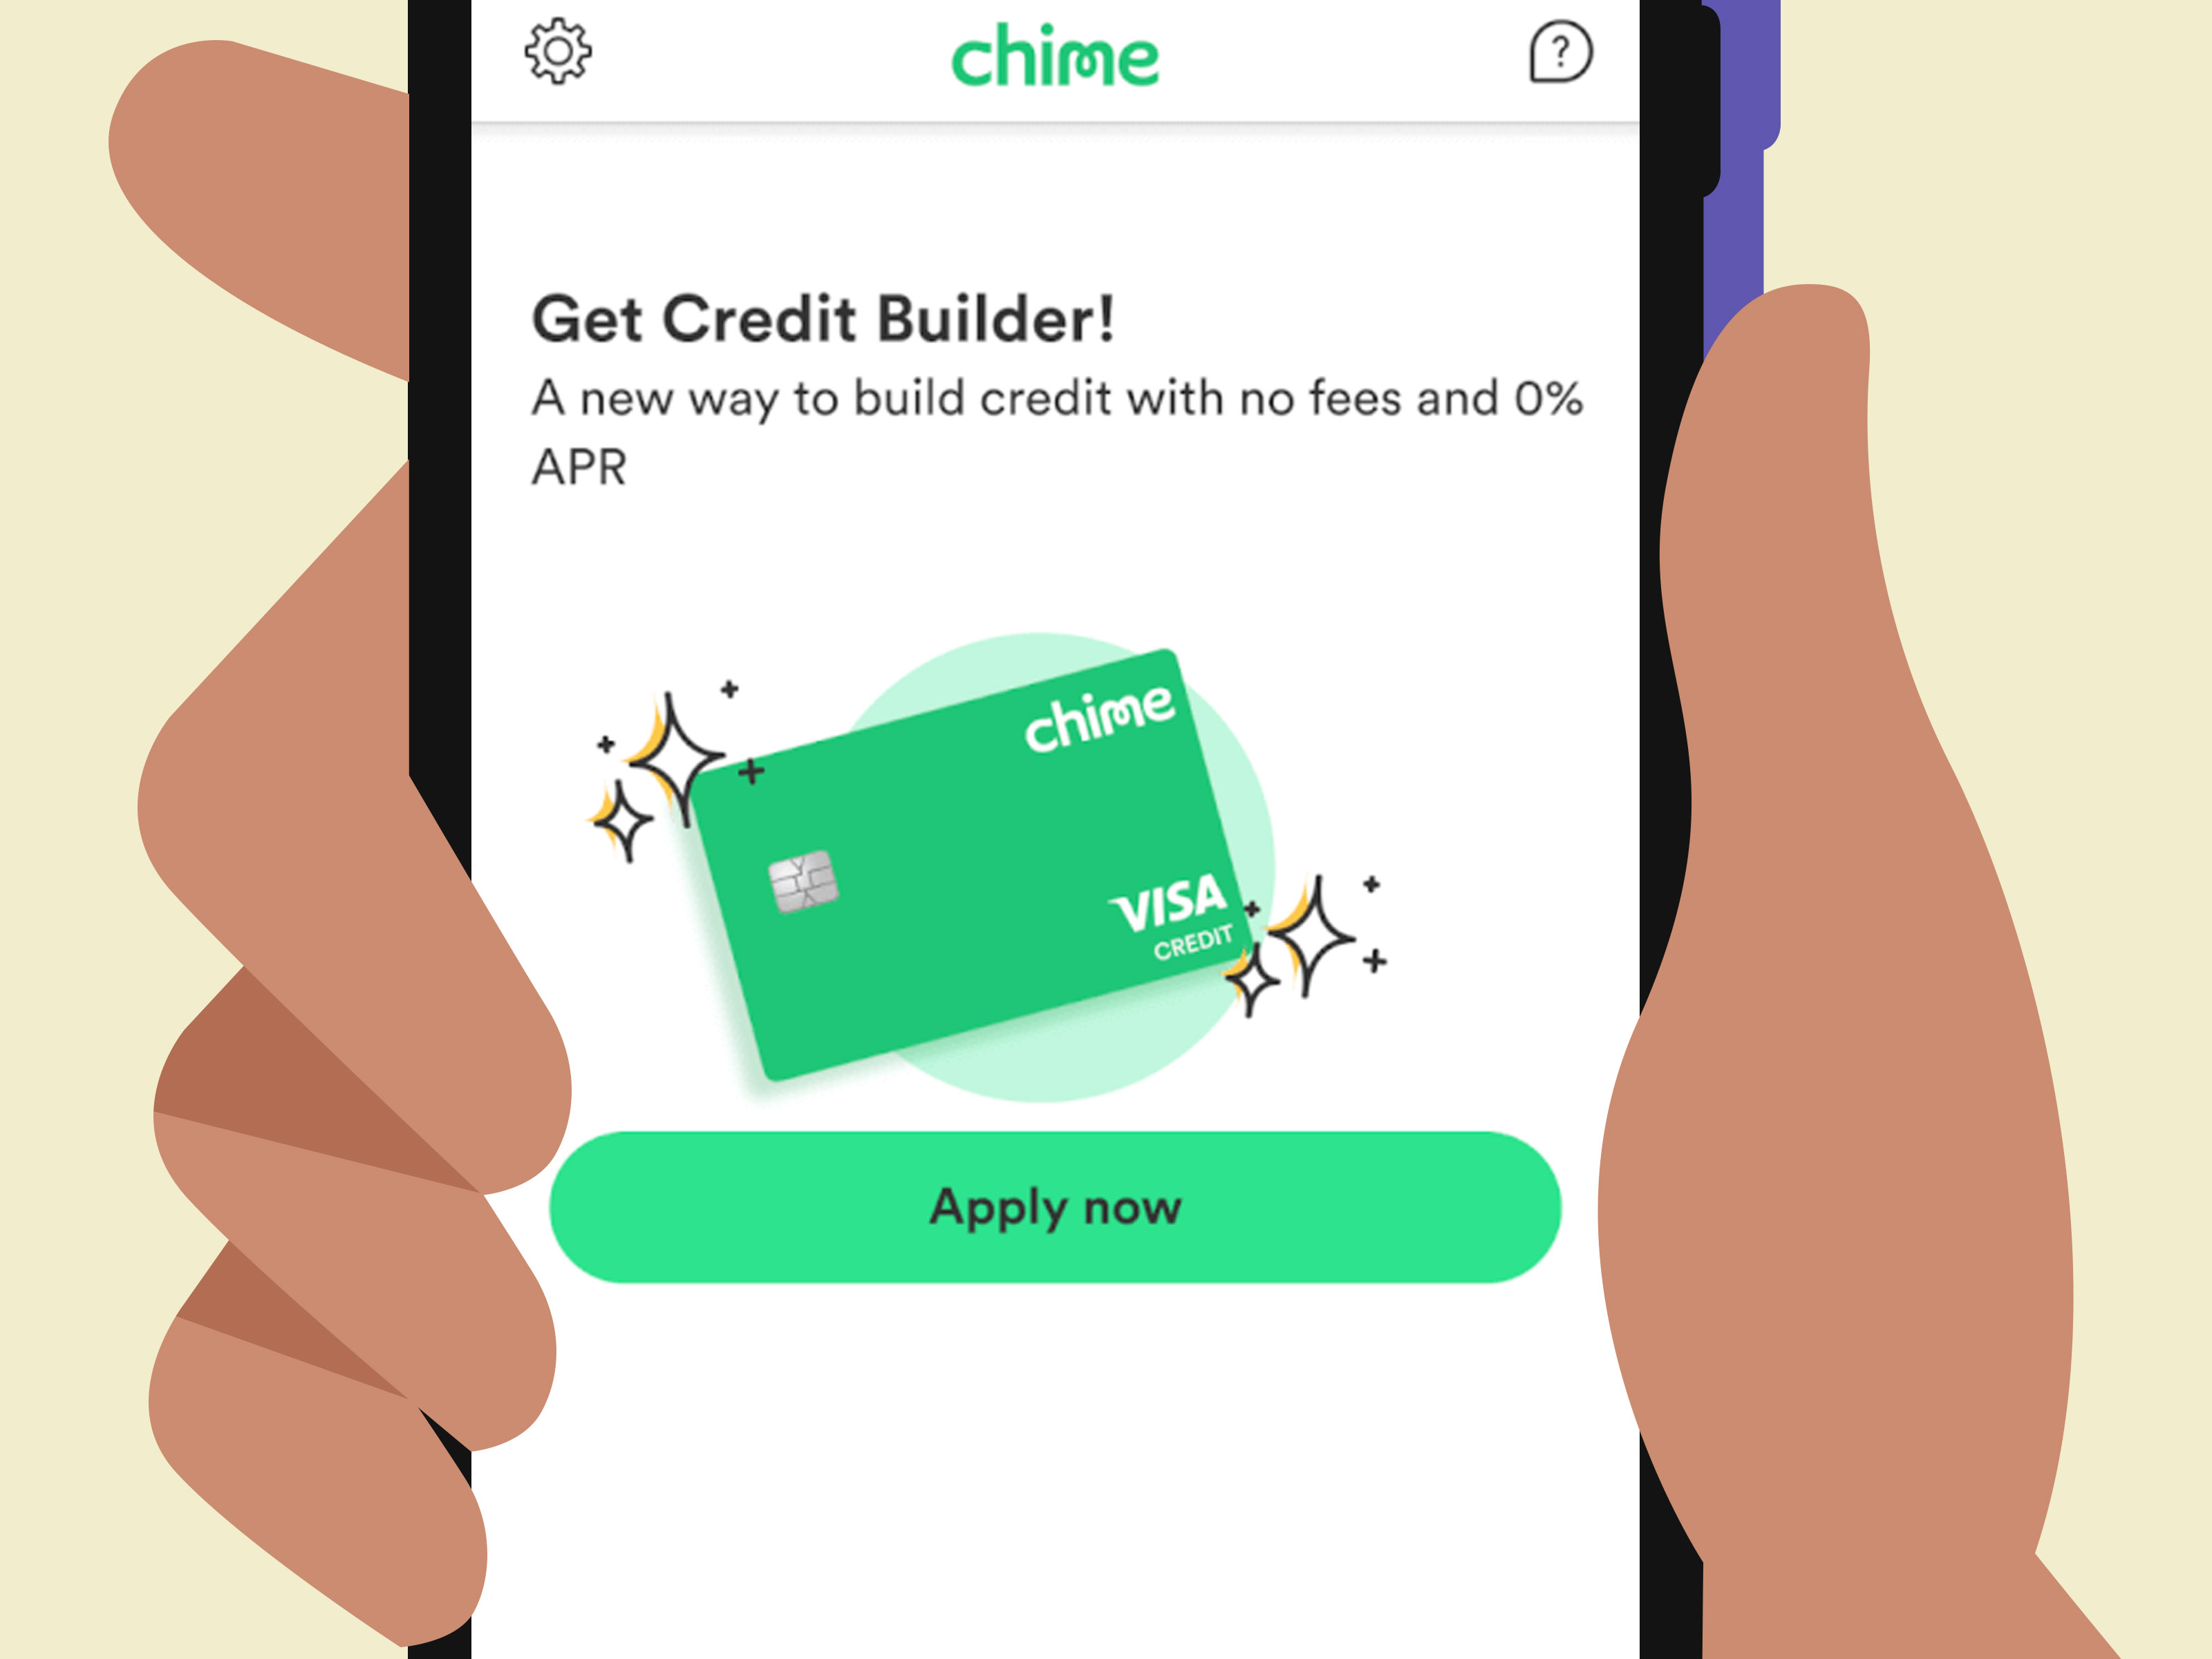

If building credit feels like trying to assemble furniture with half the instructions missing, Chime Credit Builder can look refreshingly simple. No mysterious APR traps. No traditional credit check to apply. No “oops, your $200 purchase is now wearing a tiny interest-rate backpack.” Instead, Chime’s credit-building product is designed to help people build credit history using money they already have.
There is one important update: Chime Credit Builder has evolved into the Chime Card, a secured credit card that keeps the same core missionhelping members build credit safelywhile adding newer features such as potential cash back for eligible members. Many people still search for “Chime Credit Builder,” so this guide uses both names where helpful.
So, how does Chime Credit Builder work? In plain English, you add money to a secured account, use the card for everyday purchases, and Chime reports your payment activity to the three major credit bureaus. Used consistently and paid on time, it may help you build credit history over time. It is not magic. It is not a shortcut button labeled “Excellent Credit by Friday.” But it can be a practical tool when used correctly.
What Is Chime Credit Builder?
Chime Credit Builder is Chime’s secured credit card product, now upgraded under the Chime Card name. Unlike a traditional unsecured credit card, this card is backed by money you move into your secured deposit account. That money determines how much you can spend.
Think of it as a credit card with training wheelsbut not the embarrassing kind. You still use it like a credit card wherever Visa credit cards are accepted, but you are not borrowing against a fixed bank-issued credit limit. You are spending from funds you have already set aside.
The major appeal is that Chime’s card does not charge annual fees or interest, and there is no credit check needed to apply. For people with thin credit files, damaged credit, or no credit history at all, that can make the card easier to access than many traditional credit cards.
How Does Chime Credit Builder Work Step by Step?
1. You Open or Use a Chime Account
To use Chime Credit Builder or Chime Card, you need a Chime account. Chime is a financial technology company, not a bank; its banking services and cards are provided through partner banks. Once your account is active and eligible, you can access the secured credit card feature through the Chime app.
2. You Add Money to Your Secured Account
Instead of receiving a traditional preset credit limit, you move money into the secured deposit account connected to your card. The amount available to spend is based on the money you have placed there. For example, if you move $250 into the secured account, your available spending amount is generally $250.
This is different from many secured cards that require a minimum security deposit and then hold that deposit separately until you close or upgrade the account. With Chime, the money you add is used to support your spending and can be used to pay your monthly charges.
3. You Use the Card for Everyday Purchases
You can use the Chime Credit Builder card for normal purchases like gas, groceries, subscriptions, coffee, and online shopping. The best strategy is to use it for purchases you already planned to makenot random “I deserve this” purchases at midnight. Building credit works best when your spending is boring, predictable, and paid on time.
For example, you might use the card for a $35 phone bill, a $60 grocery run, and a $20 streaming subscription. These small, manageable transactions can still create payment activity that may help build your credit history.
4. Chime Uses Your Secured Funds to Pay the Balance
At the end of the billing cycle, the amount you spent becomes your statement balance. You can pay manually, but Chime also offers a feature called Safer Credit Building. When enabled, Safer Credit Building automatically uses funds in your secured account to pay your monthly balance on time.
This feature is a big reason people like Chime Credit Builder. Payment history is the most important factor in FICO credit scoring, so automatic payment can help reduce the risk of forgetting a due date. Of course, “automatic” does not mean “ignore everything forever.” You should still check your statements, app notifications, and available balance regularly.
5. Chime Reports Payment Activity to the Credit Bureaus
Chime reports certain activity to Equifax, Experian, and TransUnion, the three major credit bureaus. Reported information can include payment status, account age, current balance, last payment date, and highest balance. This reporting is what gives the card its credit-building power.
Here is the simple formula: use the card responsibly, pay on time, let the account age, and give your credit profile time to reflect that positive activity. Credit building is more like planting a tree than microwaving popcorn. You will not see meaningful growth instantly, but consistent care matters.
Does Chime Credit Builder Really Build Credit?
Yes, it can help build credit when used responsibly. The key phrase is “can help,” not “guarantees a perfect score.” Credit scores are calculated from many parts of your credit report, including payment history, amounts owed, length of credit history, credit mix, and new credit activity.
Chime’s biggest potential benefit is payment history. Since payment history is a major part of many scoring models, on-time payments can support your credit-building journey. Chime may also help your credit history grow as the account gets older.
However, your results depend on your full credit profile. If you have other late payments, collections, high balances on other cards, or frequent new credit applications, those factors can affect your score too. Chime Credit Builder is a helpful tool, not a financial invisibility cloak.
What Makes Chime Credit Builder Different From a Regular Secured Card?
A traditional secured credit card usually requires a cash deposit, such as $200 or $500. That deposit often becomes your credit limit, but the issuer may hold the deposit until you close the account or qualify for an upgrade. You then make purchases and pay the bill like a normal credit card.
Chime works differently. The money you move to the secured account determines your available spending amount, and those funds can be used to pay your monthly charges. Chime also does not report a traditional credit limit or credit utilization percentage for the card because there is no preset credit limit.
This can be useful because credit utilizationthe percentage of available revolving credit you are usingcan strongly affect scores on traditional credit cards. With Chime, spending the amount you added does not report as high utilization in the same way. That said, balances and activity may still appear on your credit report, and your other credit accounts still matter.
Does Chime Credit Builder Have Interest or Fees?
One of the biggest attractions is that Chime Credit Builder does not charge annual fees or interest. That removes two common pain points of credit cards. You are not carrying a balance with a high APR, and you are not paying an annual fee just to keep the card open.
Still, read the fine print. Some out-of-network ATM or over-the-counter cash withdrawal fees may apply depending on how you use the card. The safest approach is to treat the card as a purchase tool, not a cash-access tool, unless you understand the fees involved.
What Is Safer Credit Building?
Safer Credit Building is Chime’s automatic payment feature. When you turn it on, Chime can automatically use money in your secured deposit account to pay your monthly statement balance. This helps reduce the risk of missed payments.
For many users, this is the “set it up before your brain forgets” feature. If you have ever remembered a bill at 11:58 p.m. with the panic of a squirrel crossing a highway, you understand the value of autopay. But again, autopay works best when you keep enough money in the secured account and monitor your activity.
Can You Miss a Payment With Chime Credit Builder?
Yes, missing a payment is possible, especially if Safer Credit Building is off or if there are not enough funds available. Chime says missed or late payments can hurt your credit, and unpaid balances may eventually affect reporting. So while the card is designed to reduce risk, it does not remove responsibility.
The best habit is simple: move money to the secured account before spending, keep Safer Credit Building enabled if it fits your needs, and review each statement. Credit building loves boring routines. Your score does not need drama; it needs consistency.
Does Chime Report Credit Utilization?
No, Chime does not report card utilization because the card does not have a preset credit limit. This is one of the product’s most unusual features. With many traditional credit cards, using too much of your available limit can hurt your score. Chime’s structure avoids reporting a standard utilization percentage for this card.
That does not mean you should spend carelessly. Your current balance and payment behavior can still matter, and your overall credit profile includes other accounts. If you have a traditional credit card with a $1,000 limit and a $950 balance, Chime will not erase that utilization problem. It is a helpful tool, not a magic eraser shaped like a debit card.
Who Is Chime Credit Builder Best For?
Chime Credit Builder may be a strong fit for people who want to build credit without a traditional credit check, people who prefer spending money they already have, and people who want guardrails against credit card debt. It can also work well for young adults, new credit users, and anyone rebuilding after past credit mistakes.
It may not be ideal if you want a large traditional credit limit, premium travel rewards, balance transfers, or a direct upgrade path to a conventional unsecured card from the same issuer. Chime is more of a credit-building starter tool than a luxury rewards card. It is practical, not flashy. More “reliable sneakers” than “designer shoes you are afraid to wear outside.”
Common Questions About Chime Credit Builder
Is Chime Credit Builder a real credit card?
Yes. It is a secured credit card that can be used wherever Visa credit cards are accepted. It is not the same as a debit card, even though the spending experience may feel similar because your available amount is tied to money you have already moved into the secured account.
Will applying hurt my credit score?
Chime says there is no credit check needed to apply, so applying does not work like a traditional credit card application that may create a hard inquiry. This can be helpful for people who are trying to avoid unnecessary credit checks.
How fast can Chime Credit Builder improve my score?
There is no guaranteed timeline. Some people may see changes after several months of on-time activity, while others may need longer. Your starting credit profile matters. A person with no credit history, a person with old late payments, and a person with high balances elsewhere may all see different results.
Can I use Chime Credit Builder for subscriptions?
Yes, many users choose small recurring bills because they are predictable. A phone bill, streaming service, or gym membership can work if you already budgeted for it. Just make sure you keep enough funds available and check that the payment processes correctly.
Is Chime Credit Builder better than a traditional secured card?
It depends on your goals. Chime is strong for low fees, no interest, no credit check, and automatic payment support. A traditional secured card may be better if you want a product that can graduate to an unsecured card, report a fixed credit limit, or offer a broader path within a major credit card issuer’s ecosystem.
Smart Ways to Use Chime Credit Builder
First, start small. Use the card for purchases you can easily afford. A $25 gas purchase paid on time is better than a $300 shopping spree that makes your budget sweat.
Second, turn on Safer Credit Building if it matches your needs. The automatic payment feature can help protect your payment history, especially if you are new to managing credit accounts.
Third, check your credit reports. Since Chime reports to the major credit bureaus, review your reports periodically to confirm that information appears correctly. Credit report errors can happen, and catching them early is much easier than discovering them when applying for a car loan or apartment.
Fourth, do not rely on one tool forever. Chime Credit Builder can be an excellent starting point, but long-term credit health may also involve managing other credit types responsibly, keeping traditional card balances low, avoiding unnecessary applications, and maintaining a clean payment record.
Real-Life Experience: What It Feels Like to Use Chime Credit Builder
Imagine someone named Alex. Alex has a thin credit file, which is a fancy way of saying lenders look at the credit report and see a tumbleweed rolling by. Alex wants to build credit but does not want a traditional credit card with interest, surprise fees, or the temptation to overspend.
Alex opens a Chime account and starts with $200 in the secured account. Instead of using the card for random purchases, Alex picks three predictable expenses: a $45 phone bill, $50 in gas, and a $25 streaming-and-music combo. Total monthly spending: $120. Nothing dramatic. No luxury vacation. No “I bought a kayak because the internet said I needed hobbies.” Just normal life.
With Safer Credit Building turned on, Alex’s monthly balance is automatically paid from the secured funds. Chime then reports the payment activity to the credit bureaus. After a few months, Alex has a growing record of on-time payments. The score may not skyrocket overnight, but the credit report begins to show responsible activity.
The experience feels closer to using a debit card with credit-building benefits than using a traditional credit card. That can be comforting for people who are nervous about debt. The guardrails are the main feature. You are spending money you already set aside, and the automatic payment option helps keep the process tidy.
But there are also lessons. Alex learns that the card is not a complete credit strategy by itself. If Alex also has another credit card with high utilization or an old unpaid collection, those issues still affect the overall score. Chime can help add positive behavior, but it cannot delete unrelated negative information.
Alex also learns that building credit requires patience. Checking a credit score every morning is like checking a plant every five minutes and yelling, “Are you a tree yet?” Credit growth usually takes months of consistent behavior. The boring habits are the powerful ones: spend lightly, pay on time, monitor reports, repeat.
Another practical experience is budgeting. Because the Chime card’s available spending is tied to money in the secured account, Alex becomes more aware of spending before purchases happen. That is different from a traditional card where a high credit limit can create the illusion of extra money. Chime’s structure gently reminds users that available credit is not free moneyit is a financial tool.
For someone rebuilding credit, the psychological benefit can be just as important as the technical one. Traditional credit cards can feel intimidating after past mistakes. Chime Credit Builder makes the process feel smaller, safer, and more manageable. It gives users a way to practice responsible credit behavior without the same level of interest risk.
Still, the best experience comes from using it intentionally. A good rule is to assign the card one job. Maybe it pays for gas. Maybe it handles one subscription. Maybe it covers groceries up to a set weekly amount. When the card has a specific purpose, it is easier to avoid messy spending and easier to track results.
In everyday use, Chime Credit Builder is best understood as a credit habit builder. The card helps create the behavior credit scoring systems like to see: repeated, on-time payments over time. It will not replace a full financial plan, but it can be a friendly starting point for people who want credit progress without the usual credit card chaos.
Final Verdict: Is Chime Credit Builder Worth It?
Chime Credit Builder can be worth it if you want a simple, low-fee way to build credit using your own money. Its strongest features are no annual fee, no interest, no credit check to apply, credit bureau reporting, and automatic payment support through Safer Credit Building.
Its limitations are also clear. It is not a premium rewards card, it does not function like a traditional unsecured credit card, and it may not offer the same upgrade path as some secured cards from major issuers. But for the right userespecially someone starting from scratch or rebuildingChime Credit Builder can be a practical, beginner-friendly credit tool.
The smartest approach is to use it consistently, spend only what you can afford, keep autopay enabled if appropriate, and monitor your credit reports. Do that, and Chime Credit Builder may help turn everyday purchases into steady credit progress. Not glamorous, maybe. But in personal finance, boring often wins.
SEO Tags